

Liquid Cooling is becoming widely adopted
We are seeing High-End chips like NVIDIA, AMD, and Google driving the adoption of liquid cooling.
Trendforce reports that:
Liquid cooling penetration among AI chips is projected to rise to 53% in 2026 and approach 60% in 2027.
High-end chips from NVIDIA, AMD, and Google are driving the adoption of liquid cooling. NVIDIA’s rack-scale solution shipments are expected to double in 2026, while more than 80% of Google’s AI servers already use liquid cooling.
It’s an interesting space to keep an eye on, because we are also seeing evidence of much higher content per AI rack.
And who benefits in this liquid cooling adoption?
Names to watch
I don’t have positions in any of these.
A QD = quick disconnect. In an AI liquid-cooling system, it is the small connector that lets you join or separate coolant lines quickly without spilling liquid.
A QD costs almost nothing relative to the AI hardware it protects, but failure is catastrophic.
small component + mission critical + hard qualification + low tolerance for failure + rapidly rising unit demand
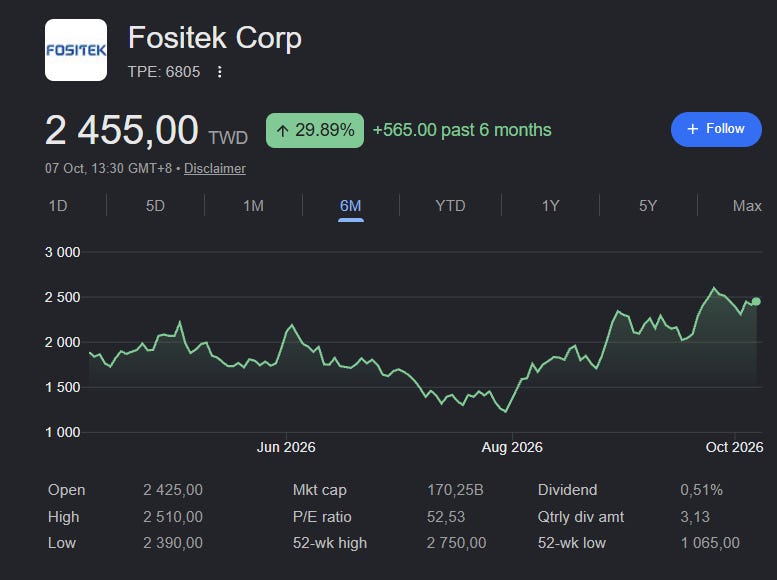
Fositek looks akin to the NHK Spring in that it manufactures this niche component- and yea, the market knows it. It trades at 26x Forward PE.
Fositek 6805.TW ~26× fwd
QD / UQD
H1 2026 server products = 55.7% of revenue, up from just 19.2% a year earlier. Full-year AI-related exposure estimated ~60%. Company does not separately disclose QD revenue. QD capacity is near full and being expanded ~50% in Q4.
NVIDIA GB200 to GB300: roughly +70% to +125% QD content.
Capacity at full & expanding, AI Racks using more QDs. Cheap component relative to full setup.
Constraints may mean price pressure comes next? (and then margins increase) - I’m postulating. Fositek seems to have the purest torque to this.
Auras 3324 .TWO ~23×PE
Cold plates, vapor chambers, manifolds, CDUs, server thermal modules
Q2 2026: server products 78% of revenue, of which water-cooling products were 55% of total company revenue.
Lotes 3533.TW ~20×PE
QD was only about 1% of August revenue, with secondary estimates suggesting it could approach ~3% by year-end as shipments ramp.
Lotes is interesting as optionality because they are exposed to many different niches in the AI Datacenter boom. They create many CPU components too for example.
Tsugami Corp. TSE:6101 15X fwd
Makes high-precision CNC automatic/Swiss-type lathes, machining centers, grinders and rolling machines. Its machines mass-produce small precision metal parts including connectors and fittings.
Its Swiss-type lathes are exactly the class of machine used to mass-produce small, tight-tolerance metal parts such as QD bodies, valve bodies, fittings, sleeves, connector components and other turned cooling hardware.
Tsugami Corp. is probably my favourite. Management is guiding flat profits for 2027 and I think they are being conservative- sandbagging. Tsugami China is literally saying the opposite (Tsugami receives royalties from China)