

I’m trying not to focus so much on the bigger names, like memory, or those names mentioned to exhaustion on X.
With “The Buildout” I’m looking for changes in architecture, and niche companies enabling those changes. Hard-to-qualify component manufacturers, and the like.
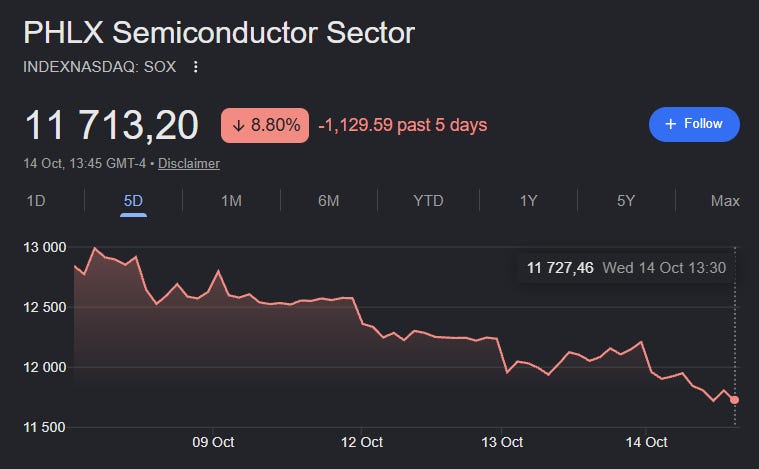
Semis are having a rough week. The market attributes the weakness to the reporting on OpenAI’s revenue, which is apparently at $50Bn annually, instead of $70Bn.
I think its more of a function of long-term interest rates and the war in Iran but who is to say? Could also just be a healthy correction from absurd prices, and then the market attaches whatever narrative it wants to that price action.
What is apparent is that semis and the big AI-exposed names, will be rife with volatility. Why wouldn’t they be?
Nobody can reliably predict how long it will take for AI to become embedded into the economy, and nobody knows what the ultimate magnitude of buildout is required- because use cases keep appearing.
Agents like Muse from Meta are in early adoption.
Video models are becoming more practical day by day.
Most enterprises still use co-pilot (which is shit).
Robotics are on the cusp.
The Sci-Fi future we saw in movies is playing out right before our eyes.
Is the buildout over? Hell no- it will just keep rotating to the next use case. Things are changing. Fast. There is opportunity in this volatility.
ASML reported today and the CEO noted:
“Our customers continue to increase their short- and medium-term equipment demand forecasts with us, driven primarily by their views on the size and duration of AI-related investments. In light of their demand visibility, some customers are expressing an interest in placing orders with us for 2029 and even 2030.”
Placing orders for 2030. Incredible.
“With such strong visibility and an order book momentum that continues to increase quarter on quarter this year, we now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers.”
Datacenter liquid cooling
I’m particularly interested in the liquid cooling space. It’s not as followed as memory, or optics, and I would like to become more familiar one some of these names before they pull a NHK Spring and their share prices launch into the stratosphere.
There are a lot of architecture changes happening within the datacenter. And with those changes come opportunity.
Fositek (6805 TW)
Fositek is probably my favourite name, but not at this price. It makes hard-to-qualify QDs which I mentioned in the previous buildout here.
At a forward price to earnings of 26x, its very expensive. As always with these kinds of ‘bottleneck’ plays, you need to be very sure of the duration of the bottleneck. And with capacity coming online from Fositek, and every Fositek competitor, it’s not really something you can be sure of. Best to wait for a real dip.
Another name I am adding to my watchlist:
BTL, Inc (6840 TW)
BTL is a potential bottleneck beneficiary of the transition toward 800V DC power architectures, megawatt-scale AI racks and liquid cooling.
These systems require increasingly complex validation and certification, supported by specialised, capital-intensive testing facilities that cannot be replicated overnight.
BTL has already secured 800V/1MW power-rack testing orders, reportedly has AI-related testing booked into Q1 2027, and is planning a new 2.5MW-capable facility. Testing revenue could grow faster than underlying AI server volumes as power density and system complexity increase.
It’s interesting because the financials look dismal, but they are securing orders and getting positioned for the demand.
In other news:
I have been absoluting scouring small-caps in Taiwan and Korea. As well as going through <$100m companies in the US to see if there’s anything new that has potential. I constantly scan the names there, I know many of them quite well. It’s how I found HRTG…didn’t stay sub $100 for long unfortunately. I am confident there will be another.